

The Institute of Internal Auditors (IIA) in Uganda is calling for the establishment of a standalone legal framework to govern the internal audit profession, arguing that its functions and responsibilities are distinct enough to warrant separate regulation from accountants.
IIA President Ruth Doreen Mutebe said internal auditing is still largely regulated under the Accountants Act, a structure she believes does not fully capture the unique nature and evolving scope of the profession in Uganda, Africa, and globally.
She stressed that the proposal is not meant to create separation or rivalry within the financial oversight ecosystem, but rather to formally recognize internal auditing as a specialised discipline that complements accounting while maintaining its own identity and standards.
Mutebe further explained that a dedicated legal instrument would strengthen professionalism, improve guidance, and enhance coordination among related fields, ultimately boosting governance and accountability across institutions.
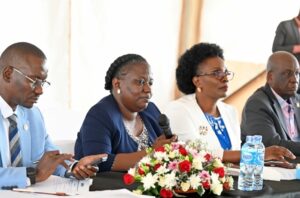
From the Ministry of Finance, Assistant Commissioner for Internal Audit Annet Musiime highlighted the critical role internal audit plays in ensuring that public resources are properly managed and directed toward intended development outcomes.
However, she acknowledged that several challenges continue to affect effectiveness, including weak risk assessment practices, limited attention from management in some institutions, and occasional breakdowns in communicating audit findings clearly and effectively.
At the Uganda Revenue Authority (URA), officials noted that the internal audit function is rapidly transforming in response to digital innovation, with systems such as e-tax and the Electronic Fiscal Receipting and Invoicing Solution improving oversight and compliance.
URA’s Acting Manager for Audit Coordination and Quality Assurance, Nicholas Asiimwe, added that auditors are increasingly relying on advanced technologies like data analytics and artificial intelligence to handle growing volumes of financial transactions, while carefully managing the risks associated with these tools to uphold transparency and integrity.